
About me · insurance professional since 1987
Your adviser,
since 1987.
My name is Roland BOUVIER, insurance specialist and wealth planning adviser. For 39 years, I have helped families, retirees and business owners prepare for their future. My job: understanding your situation, comparing the market, and standing by you.
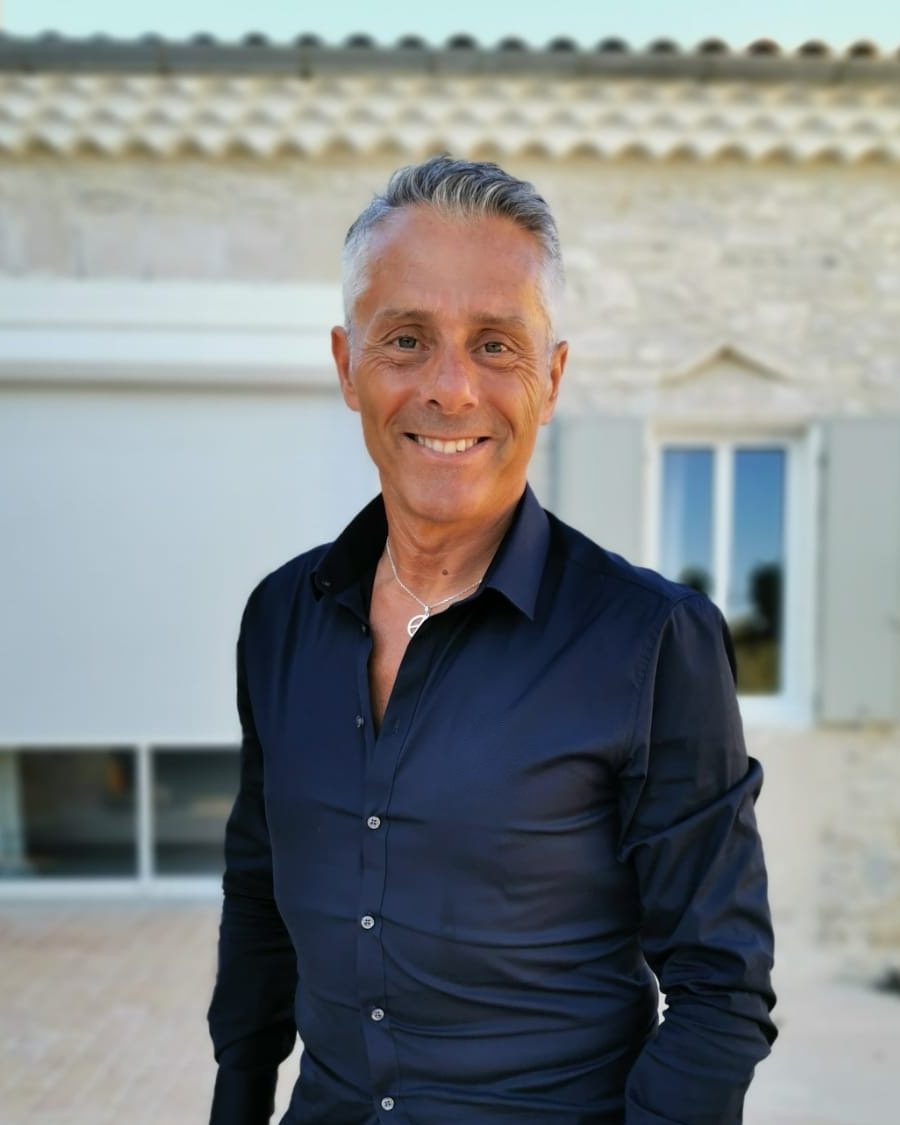
Two professions, one standard.
“I first learned the trade from the inside, working for an insurer. Then I chose independence, so as to work for one person only: my client.”
Roland BOUVIER
Tied insurance agent
Twenty years advising individuals and professionals, and getting to know contracts down to the smallest detail.
Independent broker & wealth management adviser
Choosing independence: comparing ten insurers to offer each client the most suitable solution.
A landmark, over time.
Good advice isn't given once. It is followed up, adjusted and revisited at every stage of life: a marriage, a birth, a sale, retirement.
What you can expect from me.
Independence
I work for you, not for an insurer. I compare, I negotiate, I recommend what suits you.
Clarity
Simple explanations, written recommendations, and never any needless jargon.
Loyalty
Long-term follow-up: a letter every two weeks, a review every year, a call whenever needed.
Proactive and up to date
I read geopolitics and the markets, and I use artificial intelligence to put 39 years of experience behind sounder decisions.
 Your questions
Straight answers.
Another question? Ask me directly, I'll answer personally.
Ask me a questionWhy use an independent broker?
An independent broker is not tied to any insurer. I compare offers from several insurers and choose the one that truly fits your situation: fees, cover, quality of the underlying funds.
And I remain your single point of contact, year after year, whatever the insurer.
How much does your advice cost?
The first meeting is free and with no obligation. My remuneration, and how it is calculated, is always set out in writing before you sign anything.
Is my money safe if an insurer goes bankrupt?
Insurers are closely supervised by the French prudential authority (ACPR). If one fails, it first seeks to transfer the contracts to another insurer.
As a last resort, the French life insurance guarantee fund protects your policy up to €70,000 per person and per insurer. Spreading your savings across several insurers multiplies this protection.
Can I get my money back whenever I want?
With life insurance, yes: you can withdraw all or part of your savings at any time. Tax is lighter after 8 years.
With a PER, savings are in principle locked until retirement, except to buy your main home or in the event of major life events (disability, death of a spouse, end of unemployment benefits…).
I already have contracts elsewhere. What should I do?
Nothing obliges you to change everything. I start by analysing your existing contracts: many are very good, others cost a lot for little return.
If a change is worthwhile, the law now allows a PER to be transferred, or a life insurance policy to be upgraded with the same insurer without losing its tax seniority.
What happens at the first meeting?
It lasts about an hour, at the office, at your home, by phone or by video call. We talk about your situation, your plans and your concerns.
To go further, bring your latest tax notice and your contract statements. You leave with an initial analysis, with no obligation.
Let's get acquainted.
The first meeting is free and with no obligation.